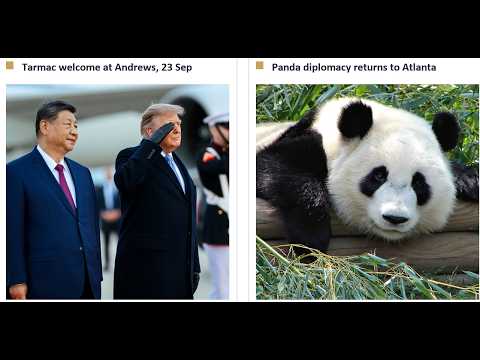
市场概述2026年9月29日
中美会谈暂缓关税与稀土限制,但台湾、芯片出口分歧仍待谈判。成品油是通胀关键变量:中国每日增100万—200万桶出口,裂解差或降至40;受限则欧洲柴油可能涨50%以上。美国通胀被判断为transitory,短期卖盘或压低市场,AI与半导体中期支撑未变。
David Hunter on the S&P 500, Bonds, Gold & Oil | What Comes Next?
David Hunter targets S&P 10,000, NASDAQ 36,000 and roughly 30–40% further upside, with a parabolic final leg if his secular-bull thesis is right.He simultaneously expects unprecedented debt and derivatives leverage to drive a potential 80% global bust, while seeing lower oil and a bond-market bull move as key cycle pivots.The timing remains unresolved: he sees a very good chance of a bust next year, but expects oil to fall and gold and silver to reach 7,000 and 200 before then.
AI spending can't grow forever with P Equity Research | EP 167
Logan JastremskiP Equity Research
AI infrastructure is constrained less by GPUs alone than by a shifting stack of memory, advanced packaging, power, construction, and networking, with memory potentially absorbing roughly half of hyperscaler capex through 2028.Long-term agreements and higher utilization may support a higher earnings floor, but cannot repeal cyclicality if ROI and free cash flow disappoint.Watch ABF, optics, and China’s potential 20-25% global memory share.
$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger creates a full-chain distributor with $75M targeted synergies and water, utilities, and data-center exposure.Buybacks at $10–12 and debt paydown support a cash-flow case, while the conservative-looking 2027 $350M EBITDA guide compares with roughly $400M on 2024 numbers.Reaching $30–32 by 2028–2029 from $16 depends on $300M 2027 FCF and re-rating, leaving ERP execution, macro recovery, and multiple expansion to monitor.
Why Natural Gas Will Be AI’s Next Great Shortage
Patrick O'ShaughnessyMatthew Smith
Matthew Smith’s model points to US natural-gas storage falling below all historical levels by 2029 as contracted LNG and AI compute outstrip deliverability, with electricity prices bearing the impact in 2028-2030.The market remains priced near $3.50-3.60, while Expand Energy and Range offer leverage to a potential physical-gas scramble; processing, pipelines, nuclear timelines, and consumer costs remain key risks.
All-In's Best Ideas Pitch Competition: 4 Investors Present Their Top Trades Live
Chamath PalihapitiyaAaron CowenDan DreyfusOleg NodelmanKyle SamaniJason CalacanisDavid SacksDavid Friedberg
MGM’s $48 bid offers a near-term floor while Osaka and possible Dubai legalization create asymmetric upside, whereas Talen monetizes a 2 GW nuclear and 6 GW gas portfolio amid a projected PJM power shortage.Aktis remains a binary 2027 clinical platform wager, and GEODNET links revenue to token purchases; portfolio sizing ultimately turns on liquidity, downside, regulatory intervention, and whether satellites displace terrestrial RTK.
Vol.218 宏观漫谈105|从AI资本市场热潮到挑战石油美元体系,历史几乎每次都一样(5.24录制)
两轮risk off后,资金重新涌入中美最拥挤的AI与机器人交易,英伟达市值升至5.5万亿美元。美国增长预期约一半建立在大型公司AI Capex持续增加之上,但低成本旧产能、企业FOMO与囤货放大了一季度表现。亚马逊可能已进入Capex超过自由现金流阶段,微软等或于明年一至二季度跟随,而token收入尚未证明商业闭环。
Alex Silver pitches BWX Technologies at Sohn 2026
BWX Technologies combines a contracted, sole-sourced government business representing 75% of revenue with 400+ Navy nuclear cores built without a safety incident and scarce licensing and manufacturing capabilities.ANM’s thesis hinges on 4–5-year time-to-power, a potential mPower-based PWR white space, and more than 100% upside from about $200, but customer interest must de-risk any updated design.
Jacob Rubin pitches Galaxy Digital at Sohn 2026
Jacob Rubin frames Galaxy Digital as a data-center opportunity, with a conservative sum-of-the-parts and CoreWeave DCF covering today’s $29-to-$30 stock while Helios combines 1.6 GW of approved power with a 15-year contract.An 830 MW customer announcement by year-end is the key catalyst; applying Hut 8’s deal math implies $13 per share, though negative cash flows, execution risk and the multiyear build remain unresolved.
Pershing Square Challenge 2026 runner-ups on Baker Hughes $BKR
Baker Hughes is pitched as a misunderstood transition from oilfield services toward IET, now roughly half the mix versus 37% in 2020, with demand potentially extending into a “2030 and beyond” story.The mechanism is turbine-tier substitution and 10-year-plus service agreements at roughly double equipment margins, while the $13.5B all-cash Chart deal offers upside but leaves integration, valuation, and governance risks to monitor.